The most common place a barndominium project dies is not the build. It's the bank.
Families come to us having picked the land, settled on a plan, and gotten comfortable with the number, only to find that the lender they've banked with for fifteen years doesn't quite know what to do with a metal- or post-framed house. That's a solvable problem, but it's much easier to solve before you're under contract on land than after.
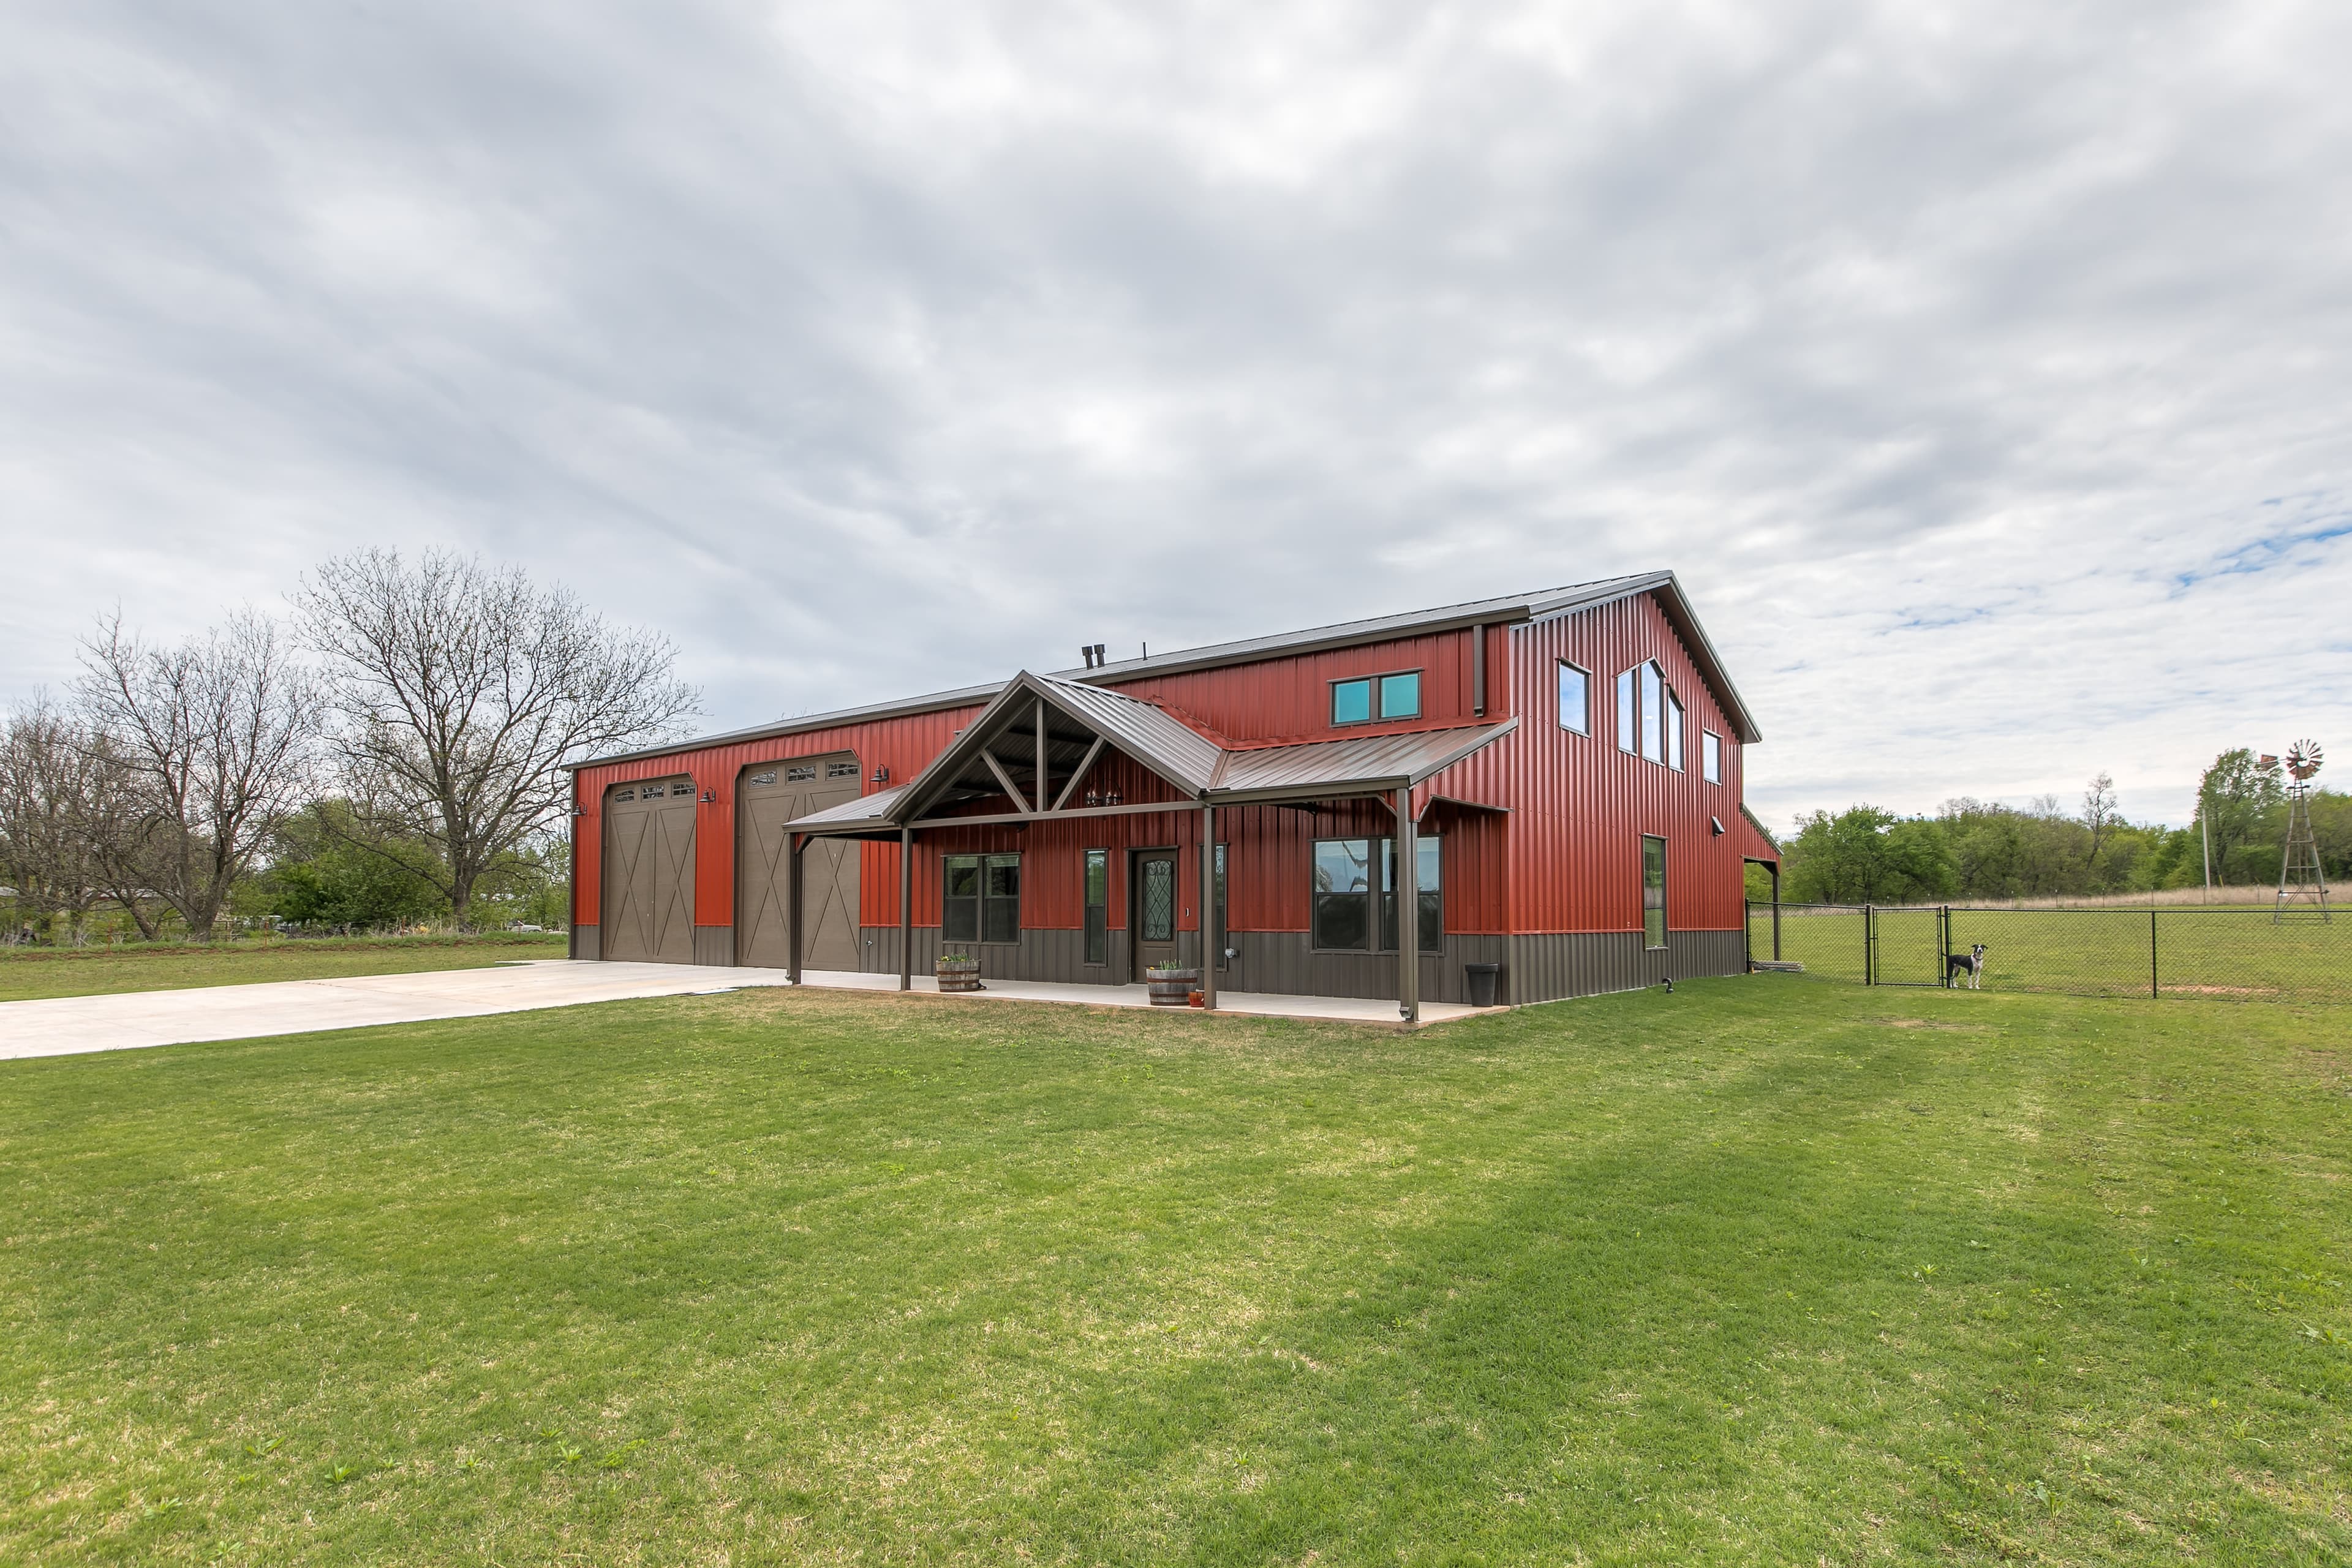
We've been building custom homes in Oklahoma since 1964. This is what we've learned about getting barndominiums financed here. For the cost side of the picture, start with our guide to what a barndominium costs to build in Oklahoma.
Why barndominium financing is different
It usually isn't the borrower. Credit, income, and down payment work the same as any custom home. The friction comes from three things specific to the build type.
Unfamiliarity. Some loan officers have simply never done one. That's not a rejection, it's a training gap, and it's why the bank down the road may say yes to exactly what your bank said no to.
Comparable sales. Appraisers value a home partly by what similar nearby homes sold for. In rural Oklahoma there may be very few recent barndominium sales within a reasonable radius, which makes the appraisal harder to support.
Who's building it. This is the big one. An experienced builder with a contract, a plan set, and a fixed price is straightforward to underwrite. A kit purchase with an owner-managed finish is a much harder file, and some lenders won't touch it.
The loan types that work
Construction-to-permanent loan
A common route, and what many of our clients use. The bank funds the build in draws as work is completed and inspected, then the loan converts to a regular mortgage at completion. You close once.
Lenders will want a full plan set, a detailed budget, a builder contract, and builder approval. Our general guide to construction loans covers how draws and inspections work, and what to expect on the down payment goes into that piece specifically.
USDA rural development loans
Much of the land people build barndominiums on in Oklahoma sits inside USDA-eligible rural areas, which is worth checking early because the down payment terms can be substantially better. Income limits and property eligibility both apply, and the property must meet the program's standards.
Conventional and portfolio loans
Possible, and portfolio lenders can be flexible because they keep the loan rather than selling it. Local and regional banks are often more comfortable with the build type than a national lender's call center. Our guide to construction loan banks in Oklahoma City and how to find the right bank are both useful here.
Land and construction together
If you don't own the land yet, some lenders will roll the land purchase into the construction loan. Others want the land owned outright or carried on a separate note first. Ask before you make an offer on a property, because the answer changes your cash requirement.
The barndominium appraisal problem
An appraisal that comes in low is the single most common way a financed barndominium stalls. The appraiser isn't being difficult; they're being asked to value something with a thin set of comparables.
Several things genuinely help:
- A complete, detailed plan set and specification. The more precisely the finished home is described, the less the appraiser has to guess.
- A builder who can supply comparable sales. We've built these across the metro and can point at real finished projects.
- Conventional residential finishes. A barndominium finished like a house appraises like a house. One finished like a shop with a bed in it appraises like a shop.
- Not over-improving for the area. The most expensive home for miles is hard to appraise regardless of how it's framed.
- Understanding loan-to-value versus loan-to-cost, which is where the gap usually shows up. We explain the difference in loan-to-value versus loan-to-cost.
What lenders will ask you for
Have these ready and the process moves considerably faster:
- A complete plan set, not a sketch
- A detailed line-item budget from the builder
- The signed builder contract, with the price and schedule in it
- The builder's license (if applicable), insurance, and references
- Proof of land ownership or the purchase contract
- Septic and water plans for rural property
- Your standard financial documents
The recurring theme is that the lender is underwriting the builder as much as the borrower. That's also why the kit-plus-owner-finish route is hard to fund, as we cover in kits vs. turnkey builds.
Insuring a barndominium
Insurance is usually straightforward and priced comparably to a traditional home, but carriers ask a few extra questions.
Expect to provide construction details, including whether the frame is steel or post-frame and how the building is clad. Some carriers rate metal buildings differently, and a few write them as commercial or agricultural structures unless you're clear that it's a primary residence. Say that plainly up front.
An attached shop can affect the policy, especially if you run a business from it. Mention it during the quote rather than after a claim. And in Oklahoma, ask specifically about the wind and hail deductible, which is where the real money sits on any policy in this state. Shop it as carefully as you shop the premium.
Practical order of operations to finance a barndominium
Do it in this sequence and most of the friction disappears:
- Choose your builder first — someone you trust to guide you through the whole process, not just swing a hammer.
- Ask that builder which lenders they've worked with, and interview those. A builder who has closed these before knows which banks say yes.
- Do both of those early, before you're under contract on land.
- Get pre-approved with a real number, not a rough figure.
- Check USDA eligibility on any property you're considering.
- Let the builder and the lender talk directly to each other rather than relaying through you.
Done in that order, you'll have the full plan set and fixed-price contract in place before the appraisal is ordered, which is exactly where you want to be.
Questions families ask us about barndominium financing
Can you get a mortgage on a barndominium?
Yes. A builder-constructed barndominium used as a primary residence is financed like any custom home, most commonly through a construction-to-permanent loan.
My bank said no. Is that the end of it?
Almost never. A "no" from one lender usually reflects that institution's experience rather than a problem with your project. Ask two more and prioritize local and regional banks.
Will the appraisal come in low?
It can, in areas with few comparable sales. A complete plan set, conventional finishes, and a builder who can supply real comps all reduce that risk considerably.
Can I finance a kit?
Financing the steel package alone is difficult, and financing an owner-managed finish is harder still. Most lenders want licensed trades and a builder contract on a home.
Does a shop hurt my loan?
Not usually, though an oversized shop relative to the living space can affect both the appraisal and the insurance classification. Worth raising with both parties early.
Talk to us before you talk to the bank
We can tell you which Oklahoma lenders have funded barndominiums we've built, and what they'll want from you. That conversation costs nothing and saves a lot of time. If you're not sure your land will support the build at all, start with a free land evaluation. No pressure and no pitch. Get in touch here.
Ready to Build Your Custom Home?
Turner & Son Homes builds on your land with a fixed-price guarantee. Let's talk about your dream home.